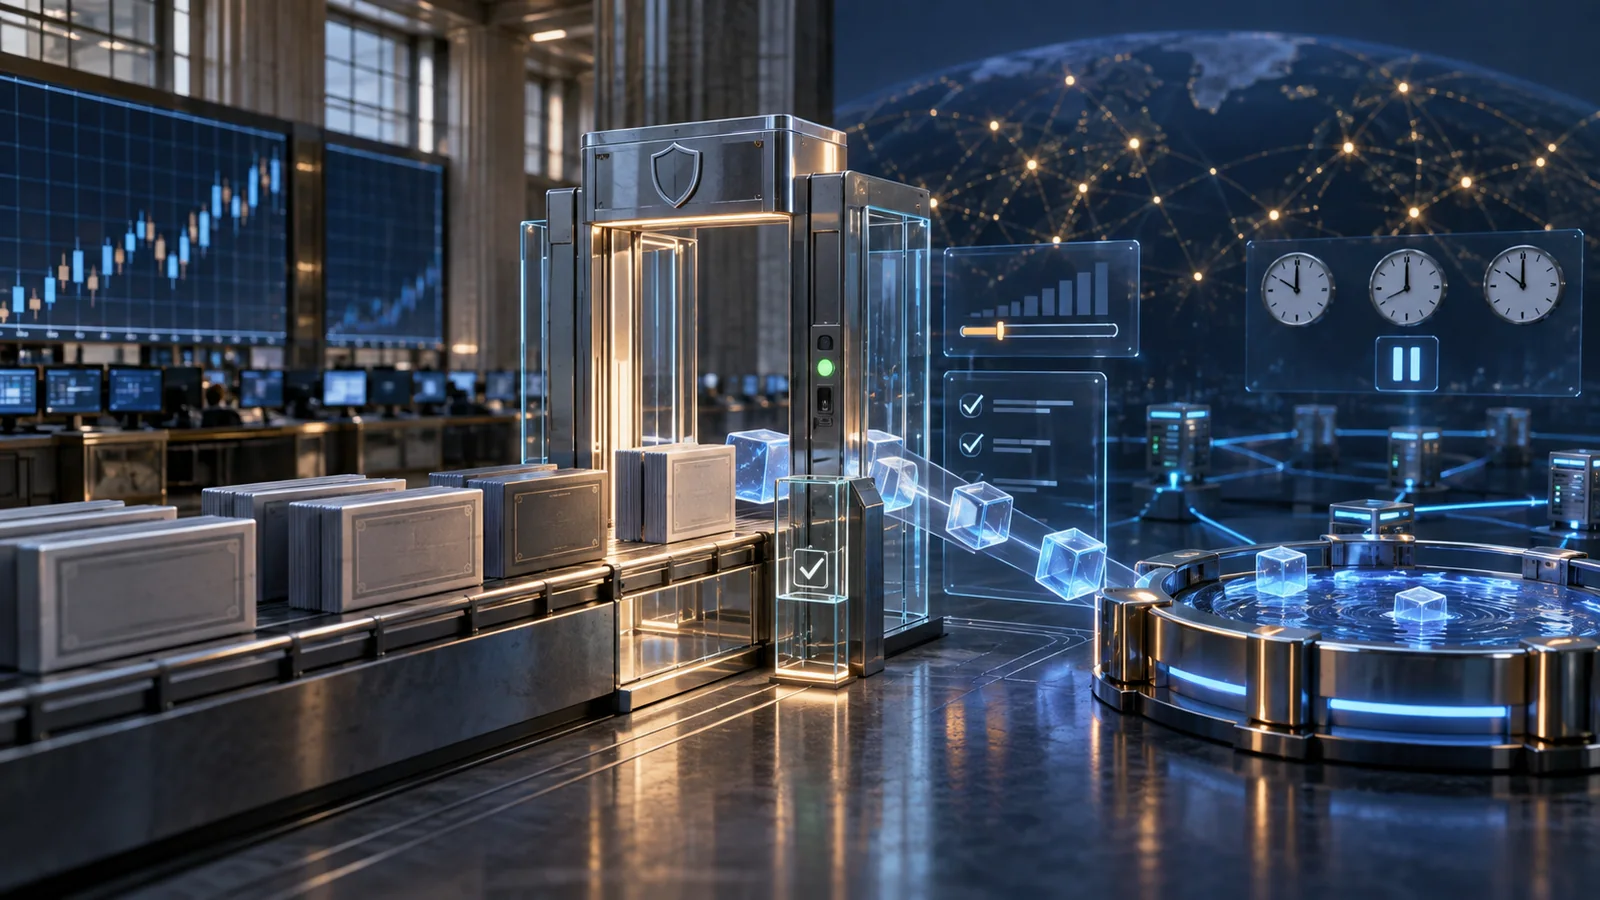
The U.S. Securities and Exchange Commission issued its “Innovation Exemption” on 17 September 2026, creating a temporary, conditional path for Tokenized Securities Venues (TSVs) and certain liquidity providers. A qualifying TSV may facilitate limited trading of tokenized National Market System stocks through permissioned automated market makers and liquidity pools deployed on a public, permissionless distributed ledger.
This is not blanket approval for tokenized shares and it does not license any named platform. The order grants narrowly conditioned relief from the Exchange Act definitions of “exchange” and, for specified liquidity providers, “dealer.” The SEC is also requesting comment and may change the longer-term framework.
Who can rely on it
A TSV brings buyers and sellers together in one or more permissioned AMM pools and sets access standards. A public blockchain therefore does not mean unrestricted participation. The venue must verify participants and meet notice, recordkeeping, operational and technology conditions.
Conditional dealer relief also applies to some liquidity providers that use proprietary capital to contribute tokenized NMS stock to a TSV pool. It does not erase broker-dealer obligations generally; activity outside the defined model still requires a separate legal analysis.
Six core safeguards
First, the number of symbols and trading volume are capped, making this a controlled experiment rather than an immediate migration of the U.S. equity market.
Second, a TSV must verify that a tokenized share gives holders the same rights and privileges as the equivalent class of conventional NMS stock. A price-tracking synthetic token is not enough.
Third, when an unaffiliated third party tokenizes the stock, the venue must give the underlying issuer written notice and an opportunity to object before trading begins. SEC commissioner statements explain that issuers can opt out.
Fourth, smart contracts must be public, auditable and deployed on a public, permissionless ledger. Code transparency does not remove risks involving bugs, oracles, privileged keys, custody or network congestion.
Fifth, trading in the tokenized stock must stop whenever the underlying stock is halted on its primary listing exchange, reducing the risk of disconnected price formation.
Sixth, the venue must publish information about its operations, trading and affiliate activity. Disclosure, records and technology safeguards are conditions of the relief, not optional best practice.
What traders should verify
Investors need to determine whether the token represents actual NMS stock with full rights, whether the venue has made the required public notice, and how legal ownership, custody and the onchain address correspond. A stock ticker or the word “stock” in a product name proves none of these points.
The order does not guarantee round-the-clock liquidity, zero slippage or instant redemption. Symbol and volume caps, issuer objections, underlying-market halts, custody and smart-contract controls can all affect availability. Product documents, shareholder rights, fees, redemption mechanics and halt procedures remain essential checks.
Impact on market infrastructure
For exchanges, brokers, custodians and tokenization providers, the significant change is that the SEC is allowing real market data to emerge within a controlled framework rather than deciding every onchain venue's permanent classification in advance. Firms must connect permissioning, KYC, ownership mapping, issuer notice, synchronized halts, contract auditability and public reporting into a verifiable system.
Corporate actions will be a major operational test. Dividends, splits, votes, mergers, freezes and corrections must remain aligned between official ownership records and blockchain tokens if equal rights are to exist in practice.
TraderVote view
The key development is not the slogan “stocks onchain,” but a usable, limited route for permissioned AMMs to trade real tokenized NMS shares. The five-year term provides room to test while preserving the SEC's ability to revise permanent rules using observed data.
The order is confirmed; approval for any existing crypto exchange is not. Offshore synthetic stock tokens cannot be assumed to qualify. A venue claiming reliance should be able to identify its public notice, eligible securities, participant controls, rights-equivalence process, issuer notice and halt coordination.
Sources
SEC press release, 17 September 2026, accessed 18 September 2026: https://www.sec.gov/newsroom/press-releases/2026-90-sec-issues-innovation-exemption-facilitate-trading-tokenized-nms-stock-request-comment
SEC Innovation Exemption fact sheet, 17 September 2026, accessed 18 September 2026: https://www.sec.gov/files/34-106402-fact-sheet.pdf
Hester M. Peirce, “Slumber Number: Innovation Exemption Statement,” SEC, 17 September 2026, accessed 18 September 2026: https://www.sec.gov/newsroom/speeches-statements/peirce-slumber-number-innovation-exemption-statement-091726
Axios, “SEC opens door for crypto-style trading of U.S. stocks,” 17 September 2026, accessed 18 September 2026: https://www.axios.com/2026/09/17/sec-tokenization-crypto-stocks
Written independently by Hengyuan from public information verifiable as of 18 September 2026. Eligibility depends on the SEC order, subsequent public notices and appropriate legal advice. This article is not investment or legal advice.
Discussion
Comments (0)
Sign in to join the discussion.
Sign inNo published comments yet. Start the discussion.