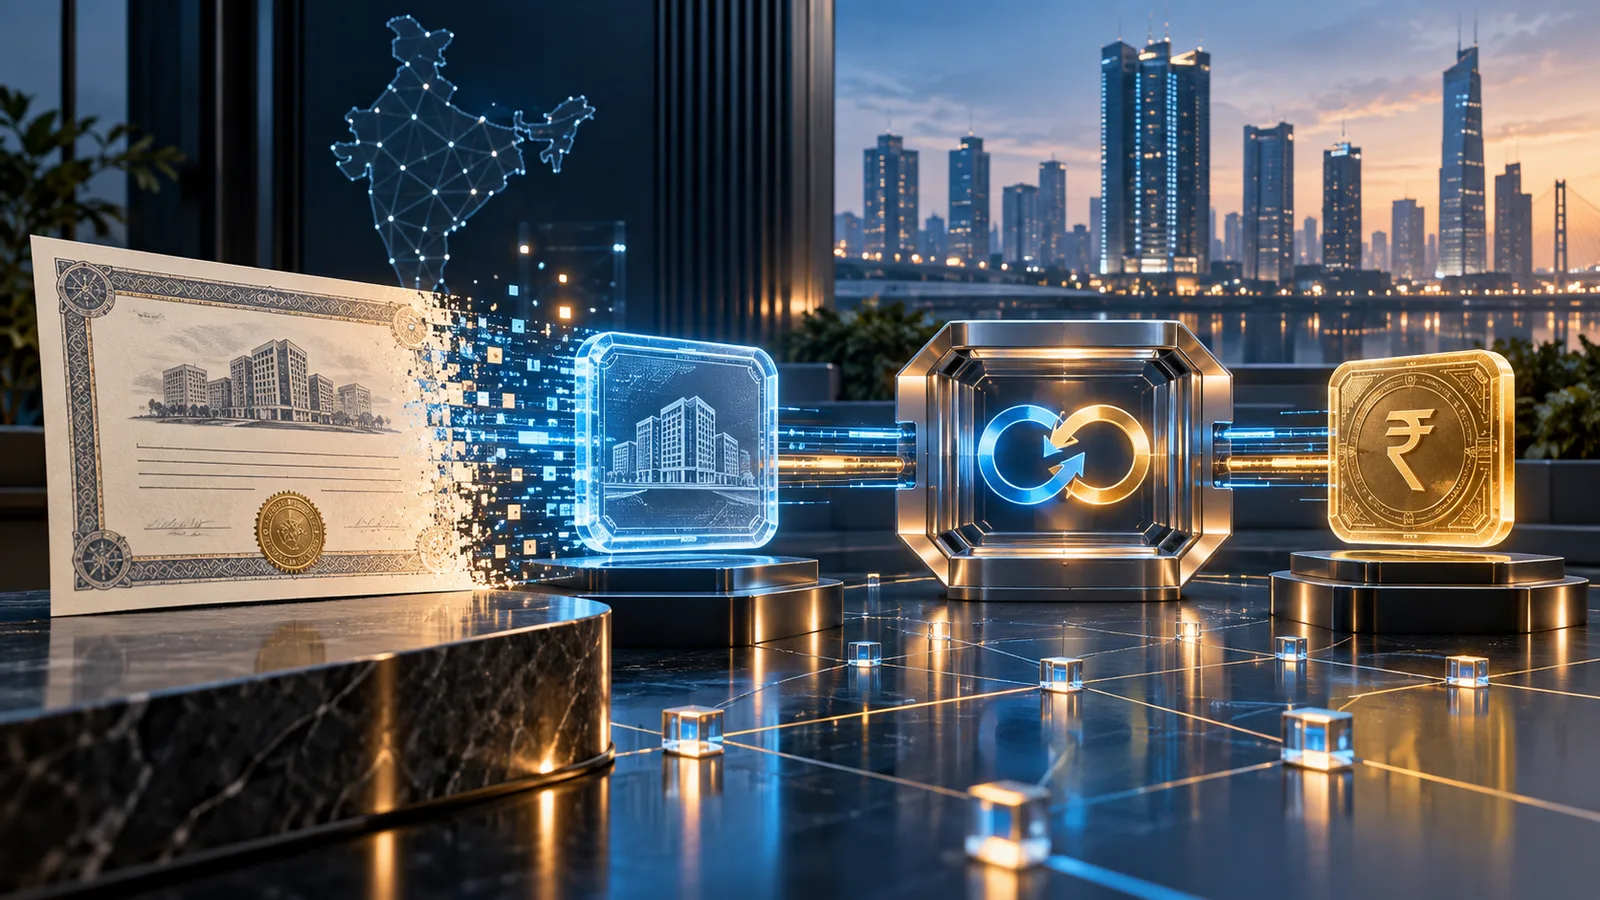
India’s Securities and Exchange Board announced the Demat 2.0 pilot for tokenised corporate bonds on 10 September. This is not a new crypto asset class. It tests issuance, holding, transfer, settlement and servicing of existing corporate bonds on a private, permissioned distributed ledger while retaining the current legal and regulatory framework.
SEBI says the token is the bond. It keeps the same ISIN, coupon, maturity, covenants, rating and investor rights. Depositories remain the authoritative record keepers, and existing rules on disclosure, listing, valuation, investor protection, freezes and attachments continue to apply.
What changes in settlement
The securities leg is linked to the Reserve Bank of India’s wholesale digital rupee. A Demat 2.0 account extends an investor’s existing demat account, uses existing KYC and is paired with a bank-provided CBDC wallet. Depositories manage private keys on investors’ behalf.
The central test is atomic delivery-versus-payment: the bond and CBDC transfers succeed together or neither settles. This is intended to remove the time gap and counterparty exposure between delivery and payment. Smart contracts may also automate scheduled coupon and redemption events, although automation does not remove issuer credit or liquidity risk.
No separate token exchange
Issuance continues through existing electronic bidding platforms. Future secondary transactions are intended to use existing RFQ and OTC-reporting channels connected to the ledger, rather than a separate token exchange.
The pilot has three proposed stages: institutional issuance and on-ledger servicing; secondary trading with possible retail access; and potential node access for rating agencies, depository participants and other regulated entities. It operates within SEBI’s regulatory sandbox, so any relief is limited in scope and time.
Moneycontrol and The Economic Times report that three issuers have already tested the system. The latter identifies REC, L&T and IIFL and reports combined issuance of ₹1,025 crore. Those transaction figures are media-reported details and should be distinguished from SEBI’s structural FAQ.
TraderVote view
The important development is the attempt to place regulated securities, central-bank money and existing trading channels in one programmable settlement path. The permissioned design preserves identifiable legal ownership and institutional controls rather than replicating anonymous public-chain markets.
Brokers, banks and market-infrastructure providers should watch smart-contract governance, wallet-to-account mapping, cyber resilience, exception handling and settlement finality. Investors should still assess issuer credit, liquidity and operational risk; tokenisation does not guarantee returns or continuous exit liquidity.
Sources
SEBI press release, published 10 September 2026, accessed 11 September 2026: https://www.sebi.gov.in/media-and-notifications/press-releases/sep-2026/successful-launch-of-demat-2-0-pilot-project-for-tokenised-corporate-bonds_104418.html
SEBI Demat 2.0 FAQ, published 10 September 2026, accessed 11 September 2026: https://www.sebi.gov.in/sebi_data/faqfiles/sep-2026/1789049630065.pdf
Moneycontrol, published 10 September 2026, accessed 11 September 2026: https://www.moneycontrol.com/news/business/markets/sebi-launches-tokenised-corporate-bond-pilot-under-demat-2-0-three-issuers-already-testing-the-system-14027289.html
The Economic Times, published 10 September 2026, accessed 11 September 2026: https://economictimes.indiatimes.com/markets/stocks/news/sebi-launches-demat-2-0-pilot-for-tokenised-corporate-bonds/articleshow/134011029.cms
Independently written by Hengyuan from public materials. This article is not investment advice.
Discussion
Comments (0)
Sign in to join the discussion.
Sign inNo published comments yet. Start the discussion.