The UK Financial Conduct Authority said on 25 September 2026 that 21 contracts-for-difference firms had closed since 2025 and three more were cancelling their permissions. Its concern is that firms conducting little substantive UK business may use FCA authorisation as a credibility badge for linked overseas companies, creating the impression that customers are contracting with a UK-regulated entity and receiving UK protections.
The announcement is not a finding that every affected firm committed fraud. The FCA did not name the 24 firms or issue the same final legal conclusion about each. Actions have included trading restrictions and independent reviews, while enforcement investigations have opened in the two most serious cases. Closure, cancellation, investigation and final sanction are different stages.
A UK licence does not cover every account under a global brand
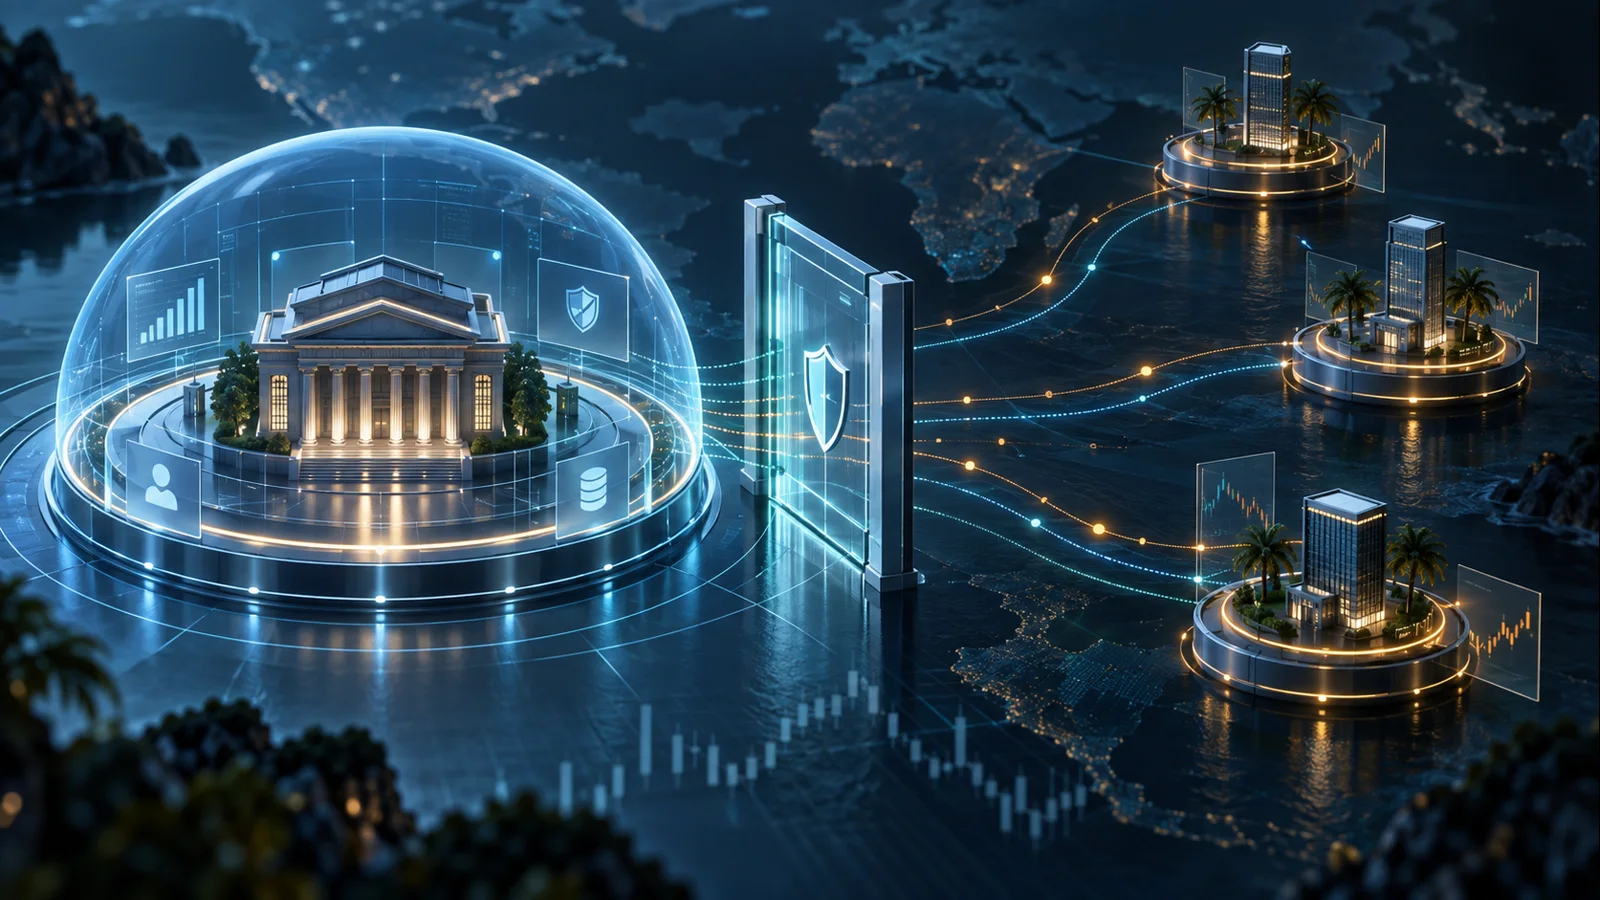
One CFD brand may operate through several legal entities. A UK company can be FCA-authorised while an affiliate elsewhere takes the customer contract, holds the money and provides the trading account. Shared branding does not by itself extend UK regulation to that overseas contract.
The practical protection boundary is usually determined by the legal name in the client agreement, the regulatory reference, client classification, receiving entity for deposits and dispute-resolution terms. A customer contracting with an offshore affiliate may not receive UK leverage limits, negative-balance protection, client-money safeguards, Financial Ombudsman access or FSCS coverage.
The FCA's December 2024 CFD strategy letter called some lightly active entities “halo firms”. It said around 20% of firms in the portfolio appeared to conduct little or no activity, and some appeared to exist mainly to give wider groups an FCA halo. The regulator said firms without material regulated activity would be invited to cancel their permissions or demonstrate a credible plan for meaningful business.
Why offshore redirection and client classification intersect
In October 2025, the FCA warned that some firms were pressuring retail customers to become elective professional clients or redirecting them to associated CFD providers in third-country jurisdictions. Either route can remove protections attached to a UK retail account.
Professional classification can affect leverage, loss protection and client-money arrangements. Offshore redirection can put the account in a jurisdiction without equivalent consumer safeguards. The 2026 closure figures show that the FCA's earlier warnings have developed into firm-level supervisory intervention.
Cross-border groups are not inherently unlawful. The questions are whether disclosures are clear, whether authorisation is used to create a misleading impression, whether the customer knowingly chooses the entity and whether the UK firm conducts genuine regulated business.
Impact on CFD groups and traders
For CFD groups, the entire customer journey must identify the service provider consistently: website, onboarding link, risk warning, agreement, payment account and support communications. Displaying a UK reference number while routing the account offshore is now an obvious supervisory risk.
The UK entity must also show that it is ready, willing and organised to conduct authorised business. Thinly staffed or inactive entities can face cancellation, closer change-of-control scrutiny and questions about whether they are effectively renting a regulatory halo.
Traders should check the full company name in the agreement against the FCA register, the permissions attached to the reference number, the name receiving deposits, retail or professional status, redirects to another domain, ombudsman and FSCS eligibility, negative-balance protection, leverage limits and client-money terms. If a salesperson says only that the “group is FCA regulated” but avoids naming the contracting entity, more verification is needed.
TraderVote view
The FCA action is an attempt to separate real regulatory coverage from borrowed credibility. Brands, platforms and support teams may be shared across borders; regulatory responsibility is not automatically shared with them.
The useful question for traders is no longer simply “Does this brand have a licence?” It is “Which entity provides my account, who holds my money and what protections apply to this exact contract?” For firms, UK authorisation must correspond to verifiable UK activity, governance and a transparent customer path—not merely a global marketing asset.
Sources
FCA, “Twenty-four CFD firms closing in crackdown on misuse of UK authorisation”, published 25 September and accessed 28 September 2026: https://www.fca.org.uk/news/press-releases/twenty-four-cfd-firms-closing-crackdown-misuse-uk-authorisation
FCA, “Portfolio Letter: FCA strategy for Contracts for Difference”, published 13 December 2024 and accessed 28 September 2026: https://www.fca.org.uk/publication/correspondence/portfolio-letter-fca-strategy-contracts-difference-2024.pdf
FCA, “FCA warns investors in CFDs risk losing out on protections”, published 30 October 2025 and accessed 28 September 2026: https://www.fca.org.uk/news/press-releases/fca-warns-investors-cfds-risk-losing-out-protections
Written independently by Hengyuan from public information verifiable as of 28 September 2026. This article is not investment or legal advice.
Discussion
Comments (0)
Sign in to join the discussion.
Sign inNo published comments yet. Start the discussion.