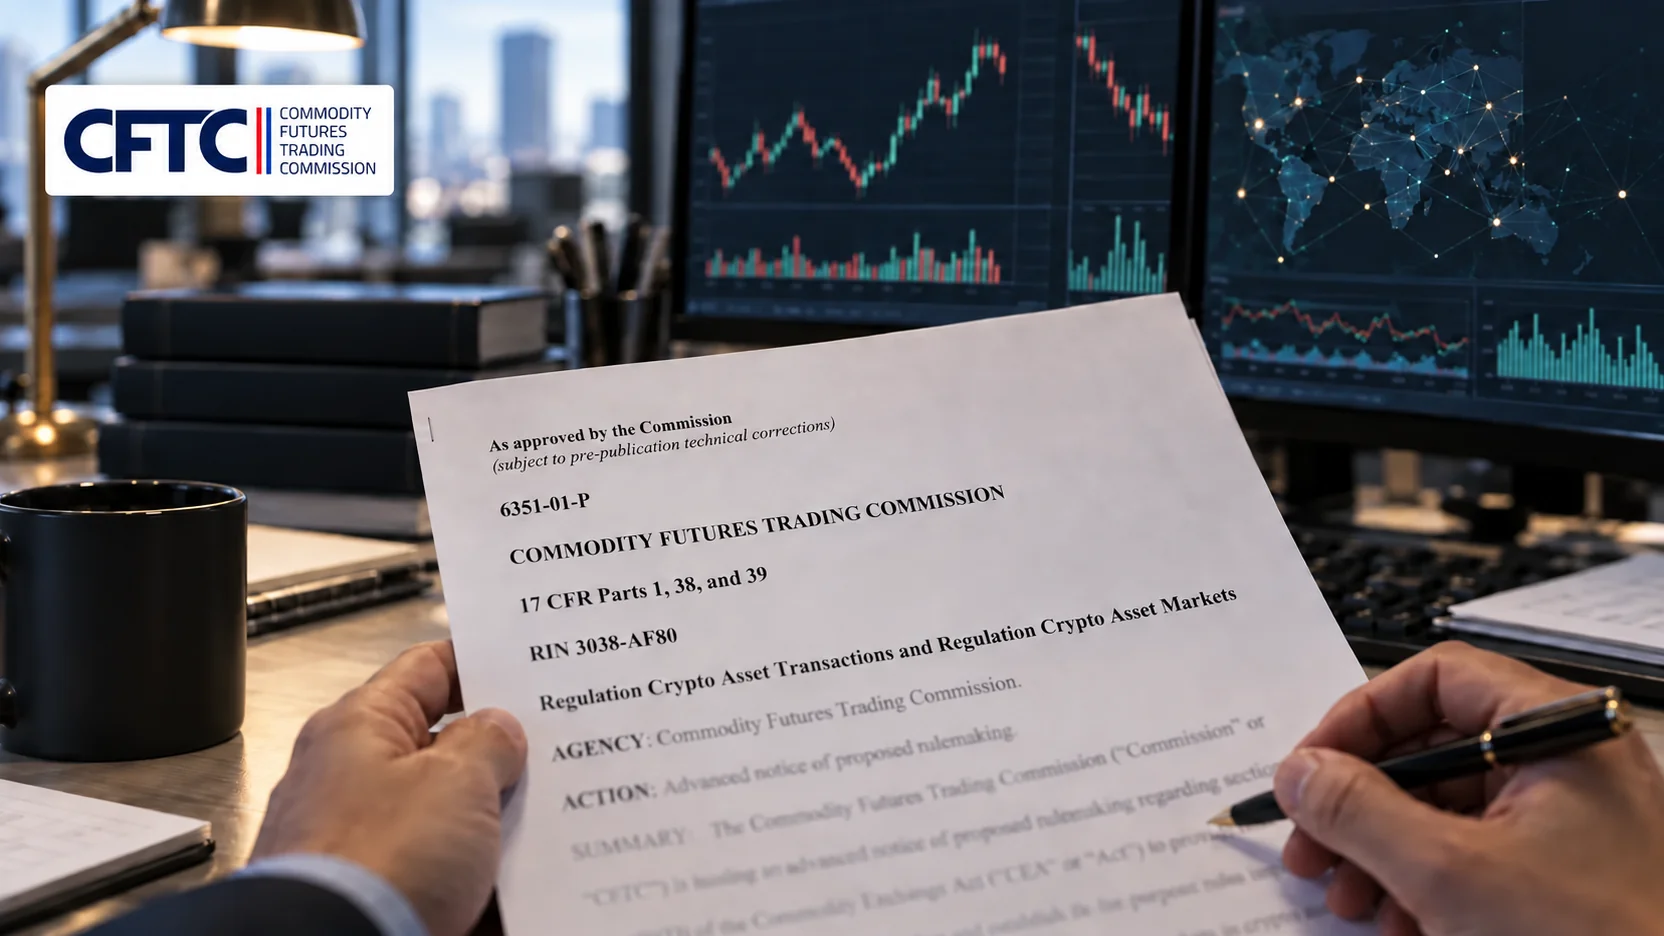
The Commodity Futures Trading Commission published release 9307-26 on 5 October together with a 108-page advance notice of proposed rulemaking, or ANPR, approved by the Commission. It seeks input on possible Regulation Crypto Asset Transactions (CTX) and Regulation Crypto Asset Markets (CAM) frameworks under existing Commodity Exchange Act authority.
The legal stage matters. This is not a final rule and not an ordinary proposed rule with settled operative text. An ANPR presents preliminary interpretations, regulatory concepts and questions to inform possible future rulemaking. The White House review record for RIN 3038-AF80 likewise identifies the action as “Prerule.”
CTX does not mean every spot trade
The document focuses on retail commodity transactions under CEA section 2(c)(2)(D) that use margin, leverage or financing and involve eligible crypto assets. The CFTC calls these CTXs.
Its preliminary view distinguishes those transactions from fully paid spot purchases that result in actual delivery. An internal exchange book entry may not give a customer meaningful possession and control. The Commission is asking how actual delivery should apply to blockchain transfers, governance rights and staking entitlements.
Chairman Michael Selig described a three-rung model in a related speech: ordinary spot venues; venues offering leveraged, margined or financed retail CTXs; and venues also offering derivatives such as perpetuals. His speech expressly says the views are his own, so the eventual Commission rule—not the analogy—will control.
A specialised CAM path under the DCM framework
The ANPR contemplates a crypto asset market as a subcategory of designated contract market registration. A venue focused only on CTXs could potentially seek a tailored federal path, while an existing DCM could offer CTXs under purpose-built requirements.
That does not compel every US spot exchange to become a CAM. The agency distinguishes state-licensed spot activity from retail margined, leveraged or financed transactions within section 2(c)(2)(D). Selig also said only Congress could require every crypto exchange to register with the CFTC.
Protections under discussion
The Commission has not fixed the obligations, but the inquiry sketches a broad architecture: DCM core principles adapted to token distribution and manipulation risks; FCM intermediation; segregation, disclosures, capital and anti-money-laundering duties; possible CAM, FCM and DCO corporate structures; custody and proof-of-reserves practices; external-wallet delivery; margin and liquidation; conflicts, system safeguards, network congestion and blockchain fees.
Proof of reserves is a consultation topic, not a current mandate. The same caution applies to FCM intermediation, capital and leverage arrangements discussed in the notice.
Comment clock and market impact
Comments are due 60 days after Federal Register publication. The 5 October release did not identify that publication date, so it should not be treated as the start of the deadline.
For traders, the most direct implications concern retail crypto products using leverage or financing. Future rules could clarify registration, customer-property safeguards, risk disclosures, liquidation and delivery. For exchanges, FCMs, custodians and clearing organisations, the hard questions concern product boundaries, organisational structure and when onchain delivery ends the full CFTC framework for a transaction.
TraderVote view
The significance is that the CFTC has assembled CTX and CAM into a coherent inquiry—not that US crypto-market legislation is complete. A tailored federal option could improve clarity for leveraged retail activity while importing traditional market-surveillance and customer-protection tools.
But spot-versus-CTX boundaries, internal ledgers, state licensing, FCM intermediation and 24/7 blockchain operations remain unsettled. Traders should not interpret an ANPR as a platform licence or as protections already in force.
Sources
CFTC release 9307-26: https://www.cftc.gov/PressRoom/PressReleases/9307-26
Commission-approved CTX/CAM ANPR: https://www.cftc.gov/media/14716/ANPRM_CTX-CAM_asapproved/download
Chairman Selig’s Fordham Law remarks, identified as his own views: https://www.cftc.gov/PressRoom/SpeechesTestimony/opaselig12
OIRA review record for RIN 3038-AF80: https://www.reginfo.gov/public/do/eo/neweomeeting?rin=3038-AF80
Written independently by Hengyuan from public information verifiable as of 6 October 2026. This article is not investment or legal advice.
Discussion
Comments (0)
Sign in to join the discussion.
Sign inNo published comments yet. Start the discussion.